
Customers are NOT willing to bail on a best-in-class product... amid a large supply shortage... during the largest tech race of our lifetime... because the vendor's CEO slept with some people.
$NVDA is just fine. Alert the presses.NVDA--

Rates still high, but AI demand is rewriting the tech playbook.

Is this a good time to start a small NVDA position?
I’ve held NVDA since 2022 and added through the dips. This whole CEO drama feels like noise compared to the AI demand. Still nervous about supply, but my portfolio needs this growth.
Not only did they offer great Q4 guidance.
But they bumped next year's growth guidance from 70% to 75% Y/Y despite the increasingly difficult comp.NVDA--
I think the upgrade is reasonable given the AI-driven demand, but I’m not convinced it’s enough to outpace the broader market. If AMD and INTC keep catching up, NVDA might still face headwinds despite the guidance.

Everyone’s cheering the 75% bump, but I’m not convinced. Guidance upgrades rarely stick when comps keep getting worse. If NVDA can’t sustain margins and data-center demand wobbles, this could be another headline pop.
They’re basically saying revenue will grow 75% next year, even with tough comps. Feels optimistic, but execution risk is real.
$NVDA's new buyback increase is worth a little more than 3 $PYPL's.NVDA--
Feels like a classic catalyst setup: NVDA buyback headline, PYPL gets a squeeze. I'm watching for a quick pop, then fade if it gaps. If it holds, I'll nibble PYPL and sell NVDA puts.

Everyone's cheering the buyback, but I'm not convinced it's sustainable. NVDA's already trading at a premium multiple, and PYPL's buyback is just a blip. If earnings don't keep rolling, this feels like a narrative boost, not a value shift.

Seen this movie: buybacks pump sentiment, but when guidance wobbles, multiples unwind fast. Keep eyes on cash burn and capex.
$NVDA data center trends are still unbelievably impressive. https://t.co/Z4wbO3UNTq
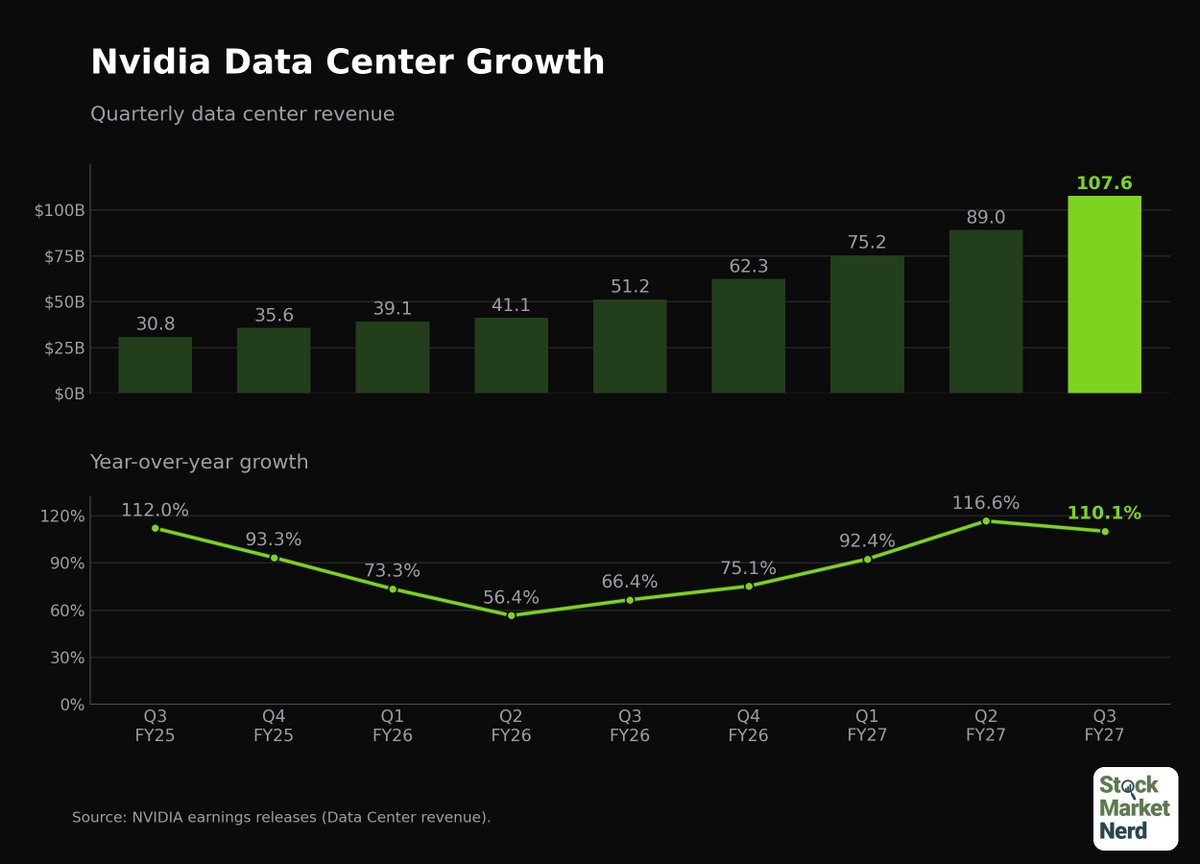
Everyone cheers growth, but margins and capex look stretched.

Seen this movie since the 2010s GPU boom and 2020 AI pivot. NVDA’s pricing power is brutal, but when demand wobbles, margins can compress fast. I’m long, but watching guidance and inventory cycles.
Feels like every headline screams “record,” but the market keeps chasing. I’m tired of hype without real execution clarity.
Q3 ahead on everything.
Guidance ahead.
Executing through all the noise. https://t.co/0FiWFb5USw


Holding NVDA and a small AMD position; the beat is nice, but I’m trimming into strength and adding a bit of SQ.

Feels like noise again; guidance ahead every quarter.
If rates stay sticky and the dollar stays firm, what’s the durable tailwind for NVDA? Supply chain bottlenecks persist, and AMD keeps catching up. Without a clear macro inflection, these beats feel like cyclical, not structural.

Everyone’s cheering NVDA’s AI growth, but I’m noticing demand softening across H10 and L4 GPUs. If enterprise budgets tighten, datacenter spend could cool faster than expected, which might cap multiples.

Feels like every earnings season we’re told AI is the future, then another quarter of bluster and inflated guidance. I’m tired of the same playbook, and the market just keeps cheering anyway.

New to this, but the AI hype around NVDA makes me excited yet nervous. Any tips for someone just starting out?
