Community/MMM
AInvest curates key KOL insights on MMM.


View post details
$WMT PRE-EARNINGS FLOW 👀
PRE-EARNINGS FLOW — Mixed in the filtered trades
• $783K in calls vs. $651.3K in puts. Puts accounted for 72.2% of contract volume.
SHORT-DATED FLOW
• 11/20 $120 calls — $152.8K ask-side block for 191 contracts.
• 11/20 $126 puts — $71K ask-side block for 200 contracts.
• 11/27 $122 and $115 puts — Opening sweeps totaling $189K across 1,370 contracts.
NET PREMIUM — Negative overall (−$927K)
• Net call premium was −$1.7M.
• Net put premium was −$766K.
EXPECTED MOVE — ±$8 (~6.3%)
• From $126.97, the post-earnings range is $118.97–$134.97.
REVENUE & EPS — Lower revenue and EPS expected QoQ
• Revenue est. $187.27B vs. $187.94B in Q2 (−0.4%).
• Adjusted EPS est. $0.63 vs. $0.81 in Q2 (−22.2%).
NOTABLE FLOW — 1/15/27 $130 calls
• $480K ask-side block for 1,000 contracts at $4.80.
• Same expiry $120 puts saw a $152.8K ask-side sweep.
GEX — Key strikes, highest first
• $135 and $130 carry +$2.6M and +$9.7M GEX for 11/20.
• $125 holds the largest positive GEX shown (+$27.4M), followed by $120 (+$19.3M) and $115 (+$12.7M).


PRE-EARNINGS FLOW — Mixed in the filtered trades
• $783K in calls vs. $651.3K in puts. Puts accounted for 72.2% of contract volume.
SHORT-DATED FLOW
• 11/20 $120 calls — $152.8K ask-side block for 191 contracts.
• 11/20 $126 puts — $71K ask-side block for 200 contracts.
• 11/27 $122 and $115 puts — Opening sweeps totaling $189K across 1,370 contracts.
NET PREMIUM — Negative overall (−$927K)
• Net call premium was −$1.7M.
• Net put premium was −$766K.
EXPECTED MOVE — ±$8 (~6.3%)
• From $126.97, the post-earnings range is $118.97–$134.97.
REVENUE & EPS — Lower revenue and EPS expected QoQ
• Revenue est. $187.27B vs. $187.94B in Q2 (−0.4%).
• Adjusted EPS est. $0.63 vs. $0.81 in Q2 (−22.2%).
NOTABLE FLOW — 1/15/27 $130 calls
• $480K ask-side block for 1,000 contracts at $4.80.
• Same expiry $120 puts saw a $152.8K ask-side sweep.
GEX — Key strikes, highest first
• $135 and $130 carry +$2.6M and +$9.7M GEX for 11/20.
• $125 holds the largest positive GEX shown (+$27.4M), followed by $120 (+$19.3M) and $115 (+$12.7M).
Like
Comment
Share
View post details
$BABA PRE-EARNINGS FLOW 👀
PRE-EARNINGS FLOW — Bearish in the filtered trades
• $1.6M in puts vs. $569.9K in calls. Put premium dominated despite calls making up 87.7% of contracts.
SHORT-DATED FLOW
• 11/27 $95 puts — $197K ask-side block for 200 contracts.
• No 11/20 trades shown in the filtered view.
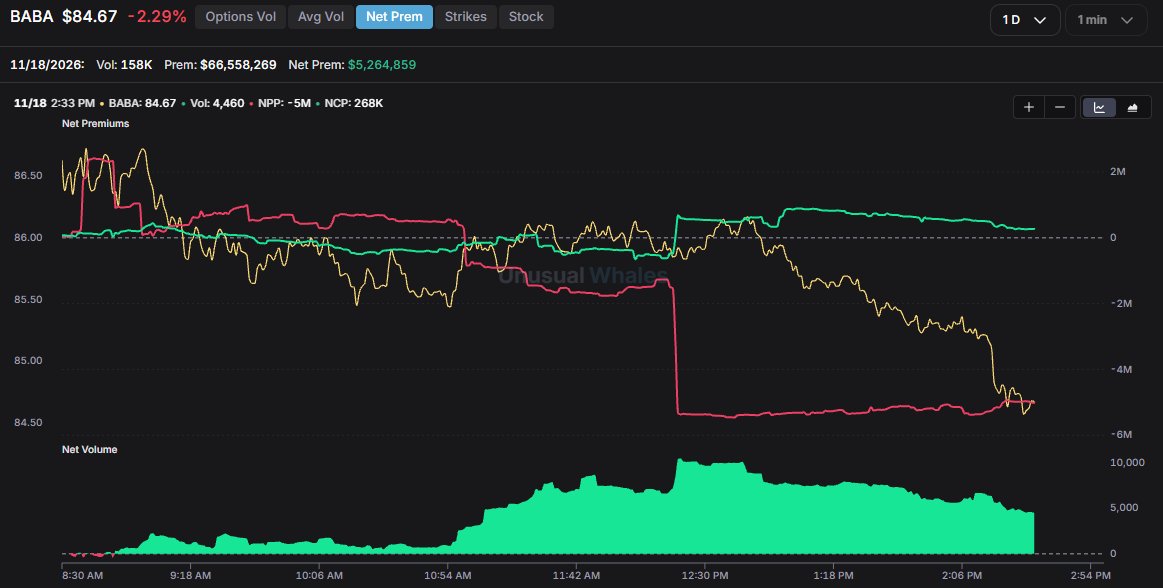
NET PREMIUM — Positive overall (+$5.26M)
• Net call premium was +$268K.
• Net put premium was −$5M.
EXPECTED MOVE — ±$6 (~7.1%)
• From $84.67, the post-earnings range is $78.67–$90.67.
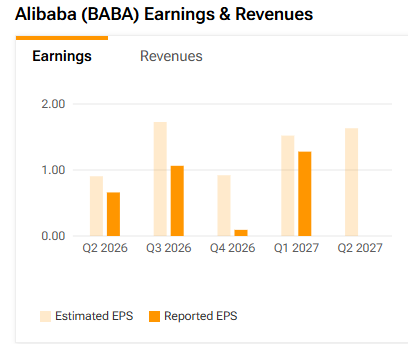
REVENUE & EPS — Higher revenue and EPS expected QoQ
• Revenue est. $40.48B vs. $39.51B in Q1 (+2.5%).
• EPS est. $1.63 vs. $1.28 in Q1 (+27.3%).
NOTABLE FLOW — 1/21/28 $140 ITM puts
• ~$1.3M ask-side sweep for 231 contracts at $55.
• 3/19/27 $135 calls saw a $224.4K block for 3,300 contracts, flagged as tied.
GEX — Key strikes, highest first
• $100 carries +$635.8K GEX for 11/20. $90 holds −$1.5M for 11/20 and −$4.7M for 12/18.
• $85 holds −$2.4M for 11/20 and −$3.9M for 12/18, followed by $80 at −$1.2M for 11/20.
PRE-EARNINGS FLOW — Bearish in the filtered trades
• $1.6M in puts vs. $569.9K in calls. Put premium dominated despite calls making up 87.7% of contracts.
SHORT-DATED FLOW
• 11/27 $95 puts — $197K ask-side block for 200 contracts.
• No 11/20 trades shown in the filtered view.
NET PREMIUM — Positive overall (+$5.26M)
• Net call premium was +$268K.
• Net put premium was −$5M.
EXPECTED MOVE — ±$6 (~7.1%)
• From $84.67, the post-earnings range is $78.67–$90.67.
REVENUE & EPS — Higher revenue and EPS expected QoQ
• Revenue est. $40.48B vs. $39.51B in Q1 (+2.5%).
• EPS est. $1.63 vs. $1.28 in Q1 (+27.3%).
NOTABLE FLOW — 1/21/28 $140 ITM puts
• ~$1.3M ask-side sweep for 231 contracts at $55.
• 3/19/27 $135 calls saw a $224.4K block for 3,300 contracts, flagged as tied.
GEX — Key strikes, highest first
• $100 carries +$635.8K GEX for 11/20. $90 holds −$1.5M for 11/20 and −$4.7M for 12/18.
• $85 holds −$2.4M for 11/20 and −$3.9M for 12/18, followed by $80 at −$1.2M for 11/20.
5
Comment
Share
View post details
🔴 $AMD 0DTE put flow spiking at $500 👀
• 11/18 $500P saw 8 ask-side sweeps totaling 3,171 contracts and $1.13M in premium
• Strike volume hit 20,649 vs. 1,223 OI
• 11/20 $520C also saw a $742.5K ask-side trade https://t.co/qlK4mmjiAO
• 11/18 $500P saw 8 ask-side sweeps totaling 3,171 contracts and $1.13M in premium
• Strike volume hit 20,649 vs. 1,223 OI
• 11/20 $520C also saw a $742.5K ask-side trade https://t.co/qlK4mmjiAO
Like
Comment
Share

View post details
$PCG calls were purchased at the ask on four different days, $6.3M in $15 strikes The most recent was $2.1M at 10:30 AM Nov 18, expiring Jan 15, 2027 Breakeven at expiry is $15.70, 15% above where the stock traded when bought Stock is up 5.1% over five days leading into a CPUC rate vote on Nov 19 A bet on a rally ahead of that vote
61
16
3
futsal212:Everyone’s cheering the pop, but I think the vote drags down sentiment. I’m leaning to fade rallies and wait for a cleaner entry.
j4_jjjj:Stock jumped, calls bought—sounds like vote hype.
See all comments

View post details
Today, one $MRVL option trade caught attention: 3,000 calls expiring in January 2027 for around $4.3M, totaling $55.1M across about 75,000 contracts, split almost equally (neutral). Stock price is now $145, down 2.4%. Excludes 0DTE contracts. Still below key averages: 50-day $224, 200-day $188. Source: GTA Terminal from Global Traders Academy.
Like
Comment
Share

View post details
$TJX Q3 earnings update: HomeGoods profit up to $443M from $344M, but Marmaxx dropped to $1.327B from $1.35B on higher sales. Tariff refunds: $132M in Q3, $55M bonus, netting 5 cents of the 1.39 EPS, no impact in Q4. Adjusted gross margin at 32.1%, down half a point due to freight and fuel costs. Is Marmaxx the Q4 game changer?
57
18
3
West-Bodybuilder-867:Volatility like this usually creates pockets: HomeGoods still outperforming, Marmaxx sales stable, and those tariff refunds look like a clean cash pulse. If margins stay sticky, I’m eyeing staggered buys into chop.
Super-Implement4739:Everyone’s fixated on HomeGoods, but Marmaxx’s stable sales and the tariff refunds suggest the real story is cost discipline. If freight normalizes, that 32% margin could creep back. I’m leaning slightly bullish on TJX.
See all comments

View post details
$PANW options today (Nov 18) saw calls favored, with about 2/3 of $63.3M in premium and 34,000 contracts traded (bullish). It's trading at $324, up 4.9%. A big single order was 830 calls expiring in Jan 2028 for around $1.0M, mostly new bets. Figures don't include 0DTE contracts. Techs: above 200-day ($279) but below 50-day ($366). Source: GTA Terminal from Global Traders Academy. Read more: https://globaltradersacademy.com/articles/palo-alto-networks-panw-institutional-flow-at-11-57-am-a-1-0m-call-bet-leads?utm_source=stocktwits
Like
Comment
Share

View post details
$ENPH might reach $17 again. The last time it hit $17 was Q3 2019 when revenue was $180MM. This quarter, revenue jumped to $293MM. Seems like a solid deal with sentiment turning negative. Of course, if war starts, sentiment could drop even more. A lot of uncertainty, but also a lot of chances.
Like
Comment
Share
View post details
$FNMA $FMCC: A resolution might be on the horizon
Since Trump's election, I still think the investment case for Fannie Mae and Freddie Mac boils down to one thing: Treasury's Senior Preferred Stock (SPS LP). Right now, Fannie and Freddie keep their profits, while the LP keeps growing. But the Twins have already paid Treasury more than the government originally gave them (about $301B vs $191B).
This leads to two different outcomes:
Bear case: Treasury keeps the SPS LP, possibly leaving common shareholders with little or no value. $FNMA and $FMCC could drop to single digits or lower.
Bull case: The SPS is seen as repaid or resolved well for common shareholders. I think shares could jump 5x from current prices, even after accounting for Treasury's warrants and dilution.
Treasury Secretary Scott Bessent said the administration plans to fix the Twins' ownership by 2027 or 2028, showing it's still on their agenda. The Treasury warrants expire in September 2028, and while that can be delayed, it's better to start now to avoid missing the mark like during Trump's first term. Trump has a reason to deliver a big policy win in his final two years and likely won't hand over control of the GSEs to Democrats.
The key takeaway: The SPS decision is mostly up to Treasury and the President. It doesn't need new laws.
Trump signed Executive Order 14393 on March 13, 2026, asking FHFA to look at housing finance markets and suggest changes. One big question is if the Enterprise Regulatory Capital Framework (ERCF) will be lowered. Some bulls expect a 2.5% capital requirement, which would improve the chances of leaving conservatorship. But changing the ERCF, including the PCCBA and PLBA buffers, takes months and is separate from the SPS issue.
In the meantime, the Twins are expanding into a tough housing market.
Some Q1 2026 figures to watch:
- Freddie Mac's multifamily business grew 24% to $12.8 billion.
- Fannie's average new loan rose from $18m to $26m.
- Fannie's full interest-only loans increased from 54% to 68%.
- Fannie's multifamily delinquencies rose 48% since December 2023.
- Fannie's multifamily write-offs hit $243m, up from $61m a year earlier.
- Losses on liquidated loans jumped from 10.4% to 18.8%.
The May 2026 ABS-15G filings showed a worrying issue. My analysis found Fannie resolved about 38% of repurchase demands, while Freddie only 3%. These demands relate to defective loans with fraud or misrepresentation, raising questions about credit quality and the impact of long-term conservatorship.
Based on my math, the Twins are still about $120B short of needed CET1 capital, equivalent to four to five years of combined earnings. The longer conservatorship lasts, the more likely institutional decline and worsening credit conditions will make an exit harder.
Next steps for the administration:
- Resolve the SPS claim, ideally treating it as repaid.
- Uplist common shares to a major exchange like the NYSE to boost institutional interest and access to capital markets.
- Keep working on capital requirements and the eventual exit through the right regulatory process.
The administration doesn't need to wait for big ERCF changes to clarify the SPS. Ultimately, I believe $FNMA and $FMCC are highly political bets. The downside is huge if Treasury keeps its claim, but the upside could be massive if the SPS is resolved in a way that helps shareholders.
With Trump's final two years, the warrants expiring in September 2028, and Bessent pointing to 2027–28 for addressing ownership, I think this is a great investment if sized right.
Since Trump's election, I still think the investment case for Fannie Mae and Freddie Mac boils down to one thing: Treasury's Senior Preferred Stock (SPS LP). Right now, Fannie and Freddie keep their profits, while the LP keeps growing. But the Twins have already paid Treasury more than the government originally gave them (about $301B vs $191B).
This leads to two different outcomes:
Bear case: Treasury keeps the SPS LP, possibly leaving common shareholders with little or no value. $FNMA and $FMCC could drop to single digits or lower.
Bull case: The SPS is seen as repaid or resolved well for common shareholders. I think shares could jump 5x from current prices, even after accounting for Treasury's warrants and dilution.
Treasury Secretary Scott Bessent said the administration plans to fix the Twins' ownership by 2027 or 2028, showing it's still on their agenda. The Treasury warrants expire in September 2028, and while that can be delayed, it's better to start now to avoid missing the mark like during Trump's first term. Trump has a reason to deliver a big policy win in his final two years and likely won't hand over control of the GSEs to Democrats.
The key takeaway: The SPS decision is mostly up to Treasury and the President. It doesn't need new laws.
Trump signed Executive Order 14393 on March 13, 2026, asking FHFA to look at housing finance markets and suggest changes. One big question is if the Enterprise Regulatory Capital Framework (ERCF) will be lowered. Some bulls expect a 2.5% capital requirement, which would improve the chances of leaving conservatorship. But changing the ERCF, including the PCCBA and PLBA buffers, takes months and is separate from the SPS issue.
In the meantime, the Twins are expanding into a tough housing market.
Some Q1 2026 figures to watch:
- Freddie Mac's multifamily business grew 24% to $12.8 billion.
- Fannie's average new loan rose from $18m to $26m.
- Fannie's full interest-only loans increased from 54% to 68%.
- Fannie's multifamily delinquencies rose 48% since December 2023.
- Fannie's multifamily write-offs hit $243m, up from $61m a year earlier.
- Losses on liquidated loans jumped from 10.4% to 18.8%.
The May 2026 ABS-15G filings showed a worrying issue. My analysis found Fannie resolved about 38% of repurchase demands, while Freddie only 3%. These demands relate to defective loans with fraud or misrepresentation, raising questions about credit quality and the impact of long-term conservatorship.
Based on my math, the Twins are still about $120B short of needed CET1 capital, equivalent to four to five years of combined earnings. The longer conservatorship lasts, the more likely institutional decline and worsening credit conditions will make an exit harder.
Next steps for the administration:
- Resolve the SPS claim, ideally treating it as repaid.
- Uplist common shares to a major exchange like the NYSE to boost institutional interest and access to capital markets.
- Keep working on capital requirements and the eventual exit through the right regulatory process.
The administration doesn't need to wait for big ERCF changes to clarify the SPS. Ultimately, I believe $FNMA and $FMCC are highly political bets. The downside is huge if Treasury keeps its claim, but the upside could be massive if the SPS is resolved in a way that helps shareholders.
With Trump's final two years, the warrants expiring in September 2028, and Bessent pointing to 2027–28 for addressing ownership, I think this is a great investment if sized right.
16
Comment
1
View post details
$PATH https://x.com/Gu23MS/status/2123064316836635022?a=dgUNIyNCn88D0vGrQng&s=02
Like
Comment
Share
View post details
$SPY $QQQ $NVDA $TSLA — NVDA beat $NVDA revenue $115.84B vs ~$109B expected, adjusted EPS $2.68 vs $2.48, data center $107.6B, Q4 guide $130B. +3.11% premarket at $160.29. Futures Wed: Nasdaq-100 +0.8%, S&P 500 +0.4%, Dow +25 pts, after Tuesday closes S&P 500 7,340.53 -1.03%, Nasdaq 24,328.38 -0.74%, Dow 50,759.42 -1.64%. TJX +5.53% premarket, Lowe's -4.97%. FOMC minutes 2pm ET. Tesla beat: JPMorgan $430 target, robotaxi fleet ~1,306 vehicles in Texas, ~5.3M unsupervised miles; Barclays Overweight $450. $TSLA closed $380.11 Tuesday. Levels first. Never guess again. ⚡ I go LIVE every weekday morning on TikTok — real-time market breakdowns, entries and exits as they happen. Tune in @positiveenergizer, 8:30am–3pm CT. Full breakdown on YouTube: Market Brief Nov 10 https://youtu.be/vBsSswQAsy4 Not financial advice. positiveenergizertrading.com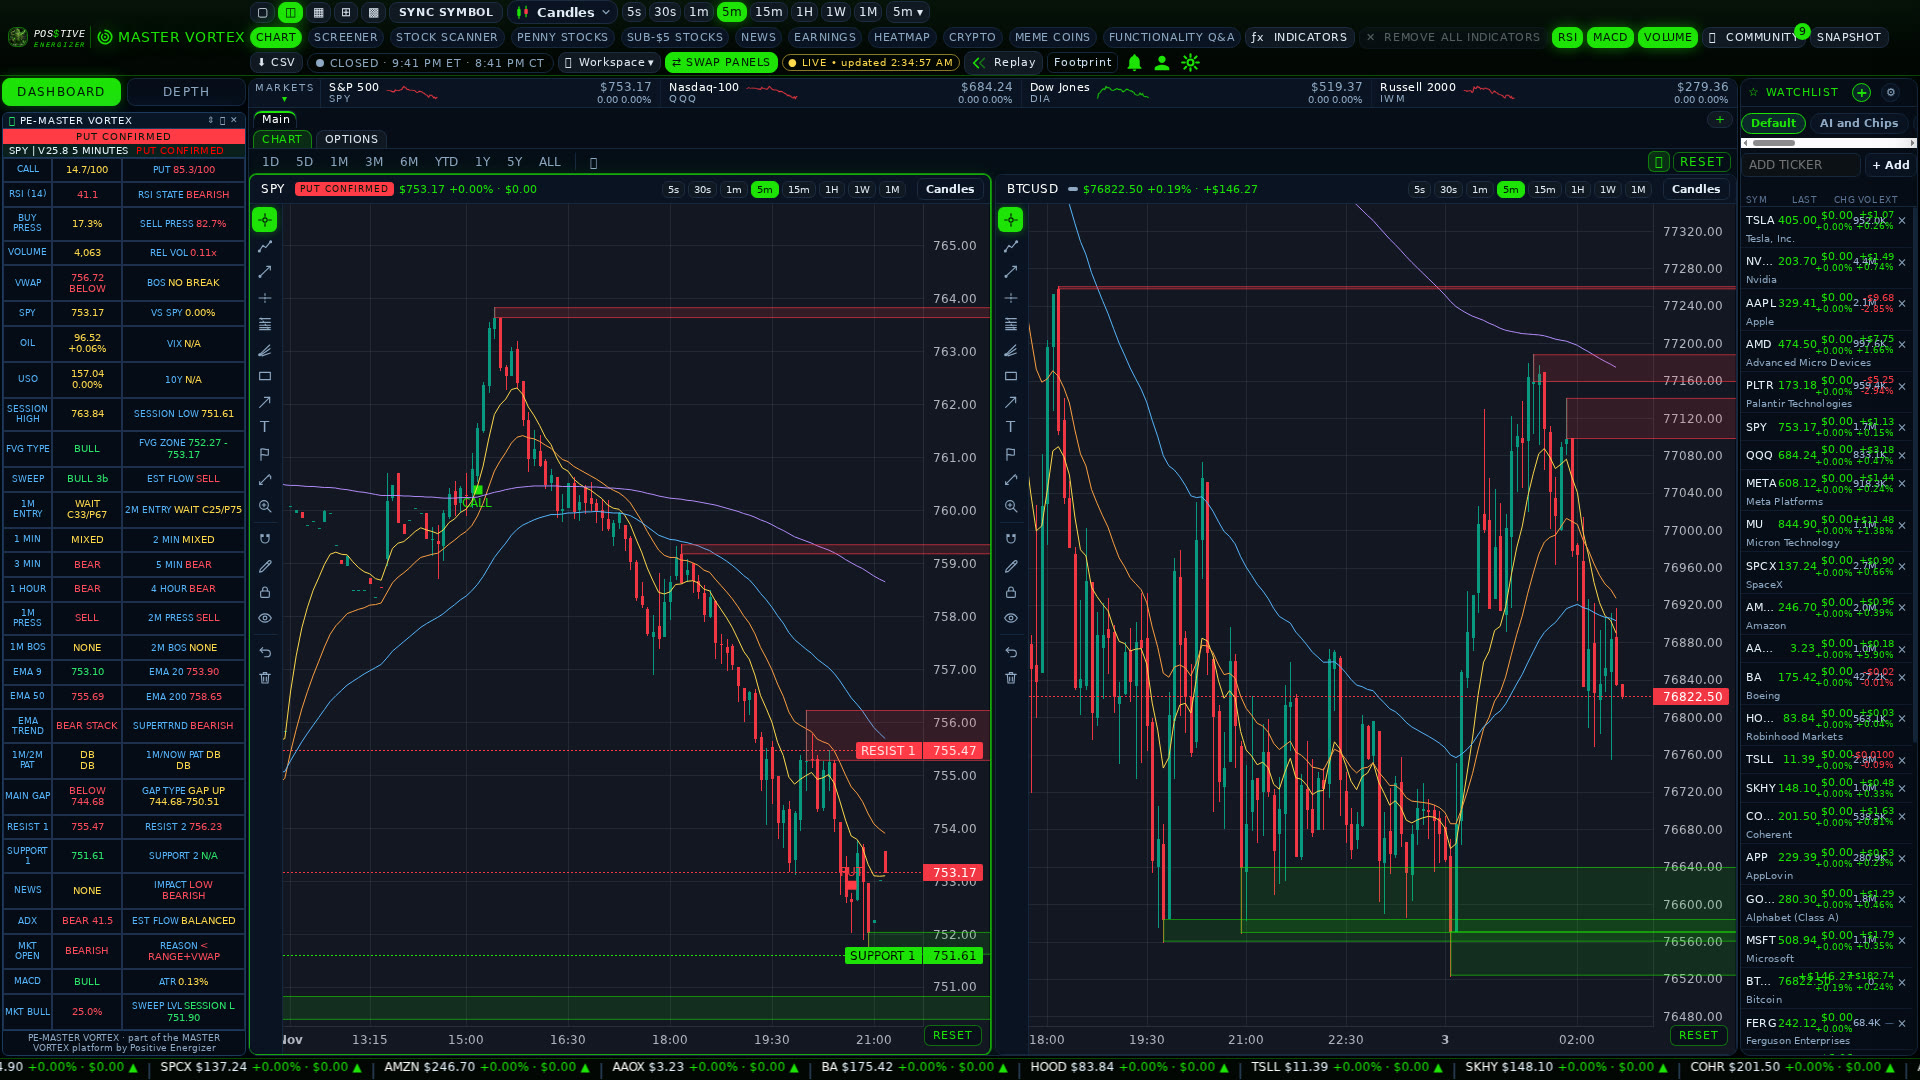
36
7
2
JoeyJensent:Given the FOMC minutes tomorrow, I’m keeping tech overweight but trimming cyclicals into strength. NVDA gets a core position, TSLA a smaller speculative sleeve, and I’ll rotate some QQQ into cash until CPI/Fed tone clears.
iamsam22222:Holding NVDA and TSLA; premarket looks juicy.
See all comments

View post details
Wall Street predicts $MMM earnings of 2.02 for Q4 [Reporting 01/26 BMO] http://www.estimize.com/intro/mmm?chart=historical&metric_name=eps&utm_cont
Like
Comment
Share
View post details
COINSHARES $CSHR SELLS ITS ENTIRE CORPORATE TREASURY $ETH POSITION AND HALF ITS $SOL TO FREE UP $19.3M FOR ITS UP TO $40M SHARE BUYBACK https://t.co/FJVeEgWSSC
29
9
3
EscapeSmall7090:If COINSHARES is buying back, expect a squeeze on CSHR and a follow-through on ETH/SOL. Watching 1.5x leverage plays.
EX-FFguy:Anyone else feel like COINSHARES is basically saying, 'We’re bullish on us' by burning ETH/SOL to fund a buyback? Does this actually signal confidence, or just a liquidity shuffle before the next dip?
See all comments
View post details
GLOBAL-E $GLBE JUST REPORTED Q3 EARNINGS
- Revenue: $314.1M, beating expectations of $313M 🟢
- EPS: $0.47, beating expectations of $0.22 🟢 (incl. tax benefit)
- GMV: $2.04B (+35% YoY)
- Adj EBITDA: $63.7M (+54% YoY)
Q4 Guidance:
- Revenue: $464M-$488M, in line with expectations of $474M 🟡
- Adj EBITDA: $113.5M-$123.5M
- GMV: $3.1B-$3.2B
Raises FY26 Guidance:
- Revenue: $1.33B-$1.35B, in line with expectations of $1.34B 🟡
- Adj EBITDA: $290M-$300M
- GMV: $8.96B-$9.12B
Key Updates:
- Share Repurchases: $53M in Q3 ($447M remaining authorization)
- Free Cash Flow: $66.4M
- Revenue: $314.1M, beating expectations of $313M 🟢
- EPS: $0.47, beating expectations of $0.22 🟢 (incl. tax benefit)
- GMV: $2.04B (+35% YoY)
- Adj EBITDA: $63.7M (+54% YoY)
Q4 Guidance:
- Revenue: $464M-$488M, in line with expectations of $474M 🟡
- Adj EBITDA: $113.5M-$123.5M
- GMV: $3.1B-$3.2B
Raises FY26 Guidance:
- Revenue: $1.33B-$1.35B, in line with expectations of $1.34B 🟡
- Adj EBITDA: $290M-$300M
- GMV: $8.96B-$9.12B
Key Updates:
- Share Repurchases: $53M in Q3 ($447M remaining authorization)
- Free Cash Flow: $66.4M
Like
Comment
Share
View post details
I was just stuck in an Ice people vortex https://t.co/qHboGl33mL


Like
Comment
Share
View post details
Whale 0xd0A4 dumped another 500,000 $UNI ($2.63M) 6 hours ago.
Over the past month, the whale has sold a total of 3.11M $UNI ($21.48M) and still holds 1.89M $UNI ($9.85M).
https://t.co/hKjJx21jbd https://t.co/Z8HTJdfz8X
Over the past month, the whale has sold a total of 3.11M $UNI ($21.48M) and still holds 1.89M $UNI ($9.85M).
https://t.co/hKjJx21jbd https://t.co/Z8HTJdfz8X
Like
Comment
Share
View post details
Sen. Chuck Schumer (@SenSchumer) criticized Trump's proposed SNAP restrictions, warning that 6.3M Americans could lose food assistance by 2029.
The USDA estimates nearly 1.8M children could also lose automatic eligibility for free school meals.
https://t.co/2A88EhJaMI
The USDA estimates nearly 1.8M children could also lose automatic eligibility for free school meals.
https://t.co/2A88EhJaMI
46
10
4
mattko:I think the real risk isn’t just hunger but political polarization. If this sticks, grocery margins might compress, but loyalty programs and SNAP redemption rates could offset. My take: watch Kroger and ALTR, not just Walmart.
MamaFen:I’m uneasy about this. SNAP cuts could spike food insecurity, which dampens consumer spending and strains local economies. I’m holding WMT and KROG for now, but I’d rather see stability than political headlines.
See all comments

View post details
$TGT PRE-EARNINGS FLOW — Bullish in the filtered trades • $648.7K in calls across 2,915 contracts vs. $77K in puts across 200 contracts. SHORT-DATED FLOW — 11/20 expiry (3 DTE) • Two ask-side trades hit the $170 calls • The $150 puts saw 200 contracts trade at the ask for $77K. NET PREMIUM — Positive overall (+$1.66M) • Net call premium was +$805K. • Net put premium was −$852K. EXPECTED MOVE — ±$11 (~6.9%) • From $158.85, the implied post-earnings range is $147.85–$169.85. • The $170 call strike sits just above the upper end. REVENUE & EPS — Slightly lower revenue and lower EPS expected QoQ NOTABLE FLOW — 11/20 $170 calls • $413.2K ask-side block for 1,904 contracts at $2.17. • $235.6K ask-side sweep for 1,011 contracts at $2.33. GEX — Key strikes, highest first • 11/20 — $180 +814.9K | $175 +985.3K | $170 +2M | $165 +1.1M | $150 −483K | $140 −545.5K • 11/27 — $175 +1.9M | $170 +407.8K | $165 +3.3M | $160 −390.8K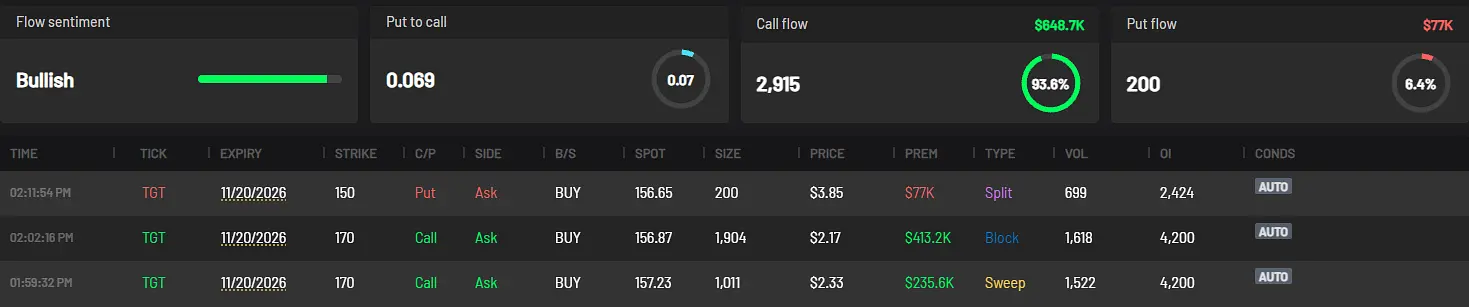
Like
Comment
Share
View post details
https://t.co/3M64VBQhpd
55
12
5
diffvinra:Everyone's bracing for a brutal selloff, but I think the panic is already priced. Liquidity's still there, earnings quality hasn't collapsed, and a surprise dovish pivot could flip risk appetite fast.
Accomplished_Dot9815:Not thrilled by the noise, but I'm sticking with my core; compounding needs patience, not perfect timing.
See all comments
View post details
$NVDA PRE-EARNINGS FLOW :eyes:
NET PREMIUM
• −$80.76M overall | Net calls −$47.9M | Net puts +$31.9M
PRE-EARNINGS FLOW
• The flow scanner showed $81.6M in calls vs. $49.5M in puts, with a 0.76 put/call volume ratio.
SHORT-DATED FLOW
• 11/18 $160C saw three ask-side sweeps totaling 1,233 contracts and $486K.
• 11/20 $160C saw another $100K ask-side sweep.
• 11/18 $152.50P saw a $160K ask-side sweep.
EXPECTED MOVE
• ±$11 post-earnings (~7.2%), implying roughly $142–$164 from $152.90.
EXPECTED REVENUE & EPS VS. PRIOR QUARTER
• Revenue consensus of $108.96B vs. $96.22B last quarter (+13.2% QoQ).
• EPS consensus of $2.48 vs. $2.22 adjusted EPS last quarter (+11.7% QoQ).
NOTABLE FLOW
• 12/18 $160P — $2.92M ask-side block, flagged as a spread leg.
• 2/19/27 $185C — $548K ask-side split.
GEX
• 11/18 — $175 +3.5M | $170 +5M | $150 −7.9M | $145 −8.2M
• 11/20 — $177.50 +10.3M | $172.50 +8.5M | $160 −11.1M | $150 −19M | $145 −8.7M


NET PREMIUM
• −$80.76M overall | Net calls −$47.9M | Net puts +$31.9M
PRE-EARNINGS FLOW
• The flow scanner showed $81.6M in calls vs. $49.5M in puts, with a 0.76 put/call volume ratio.
SHORT-DATED FLOW
• 11/18 $160C saw three ask-side sweeps totaling 1,233 contracts and $486K.
• 11/20 $160C saw another $100K ask-side sweep.
• 11/18 $152.50P saw a $160K ask-side sweep.
EXPECTED MOVE
• ±$11 post-earnings (~7.2%), implying roughly $142–$164 from $152.90.
EXPECTED REVENUE & EPS VS. PRIOR QUARTER
• Revenue consensus of $108.96B vs. $96.22B last quarter (+13.2% QoQ).
• EPS consensus of $2.48 vs. $2.22 adjusted EPS last quarter (+11.7% QoQ).
NOTABLE FLOW
• 12/18 $160P — $2.92M ask-side block, flagged as a spread leg.
• 2/19/27 $185C — $548K ask-side split.
GEX
• 11/18 — $175 +3.5M | $170 +5M | $150 −7.9M | $145 −8.2M
• 11/20 — $177.50 +10.3M | $172.50 +8.5M | $160 −11.1M | $150 −19M | $145 −8.7M
42
11
2
coco88888:Feels like the market’s chasing every tiny pop again. NVDA pre-earnings flow looks messy, and the premium’s eating everyone’s stops.
Cgbt123:Revenue and EPS growth still look solid despite choppy options.
See all comments
Disclaimer: the above is a summary showing certain market information. Ainvest is not responsible for any data errors, omissions or other information that may be displayed incorrectly as the data is derived from a third party source. Communications displaying market prices, data and other information available in this post are meant for informational purposes only and are not intended as an offer or solicitation for the purchase or sale of any security. Please do your own research when investing, All investments involve risk and the past performance of a security, or financial product does not guarantee future results or returns. Keep in mind that while diversification may help spread risk it does not assure a profit, or protect against loss, in a down market.
Trending
Hot Topics
Nvidia Doubles Revenue, Stock +6%: Real Rally or Bull Trap?
NEW
418 Posts
BTC Back Above $65K, Fear at 11: Buy or Wait?
HOT
212 Posts
ANT Debuts Thursday at $1.4T: Six Times Bid, Buy or Bail?
690 Posts
BTC Breaks 200-Week MA: $52K Next?

712 Posts
Huang Plots Return, Bessent Says No: NVDA -25% Reports Tue

1962 Posts